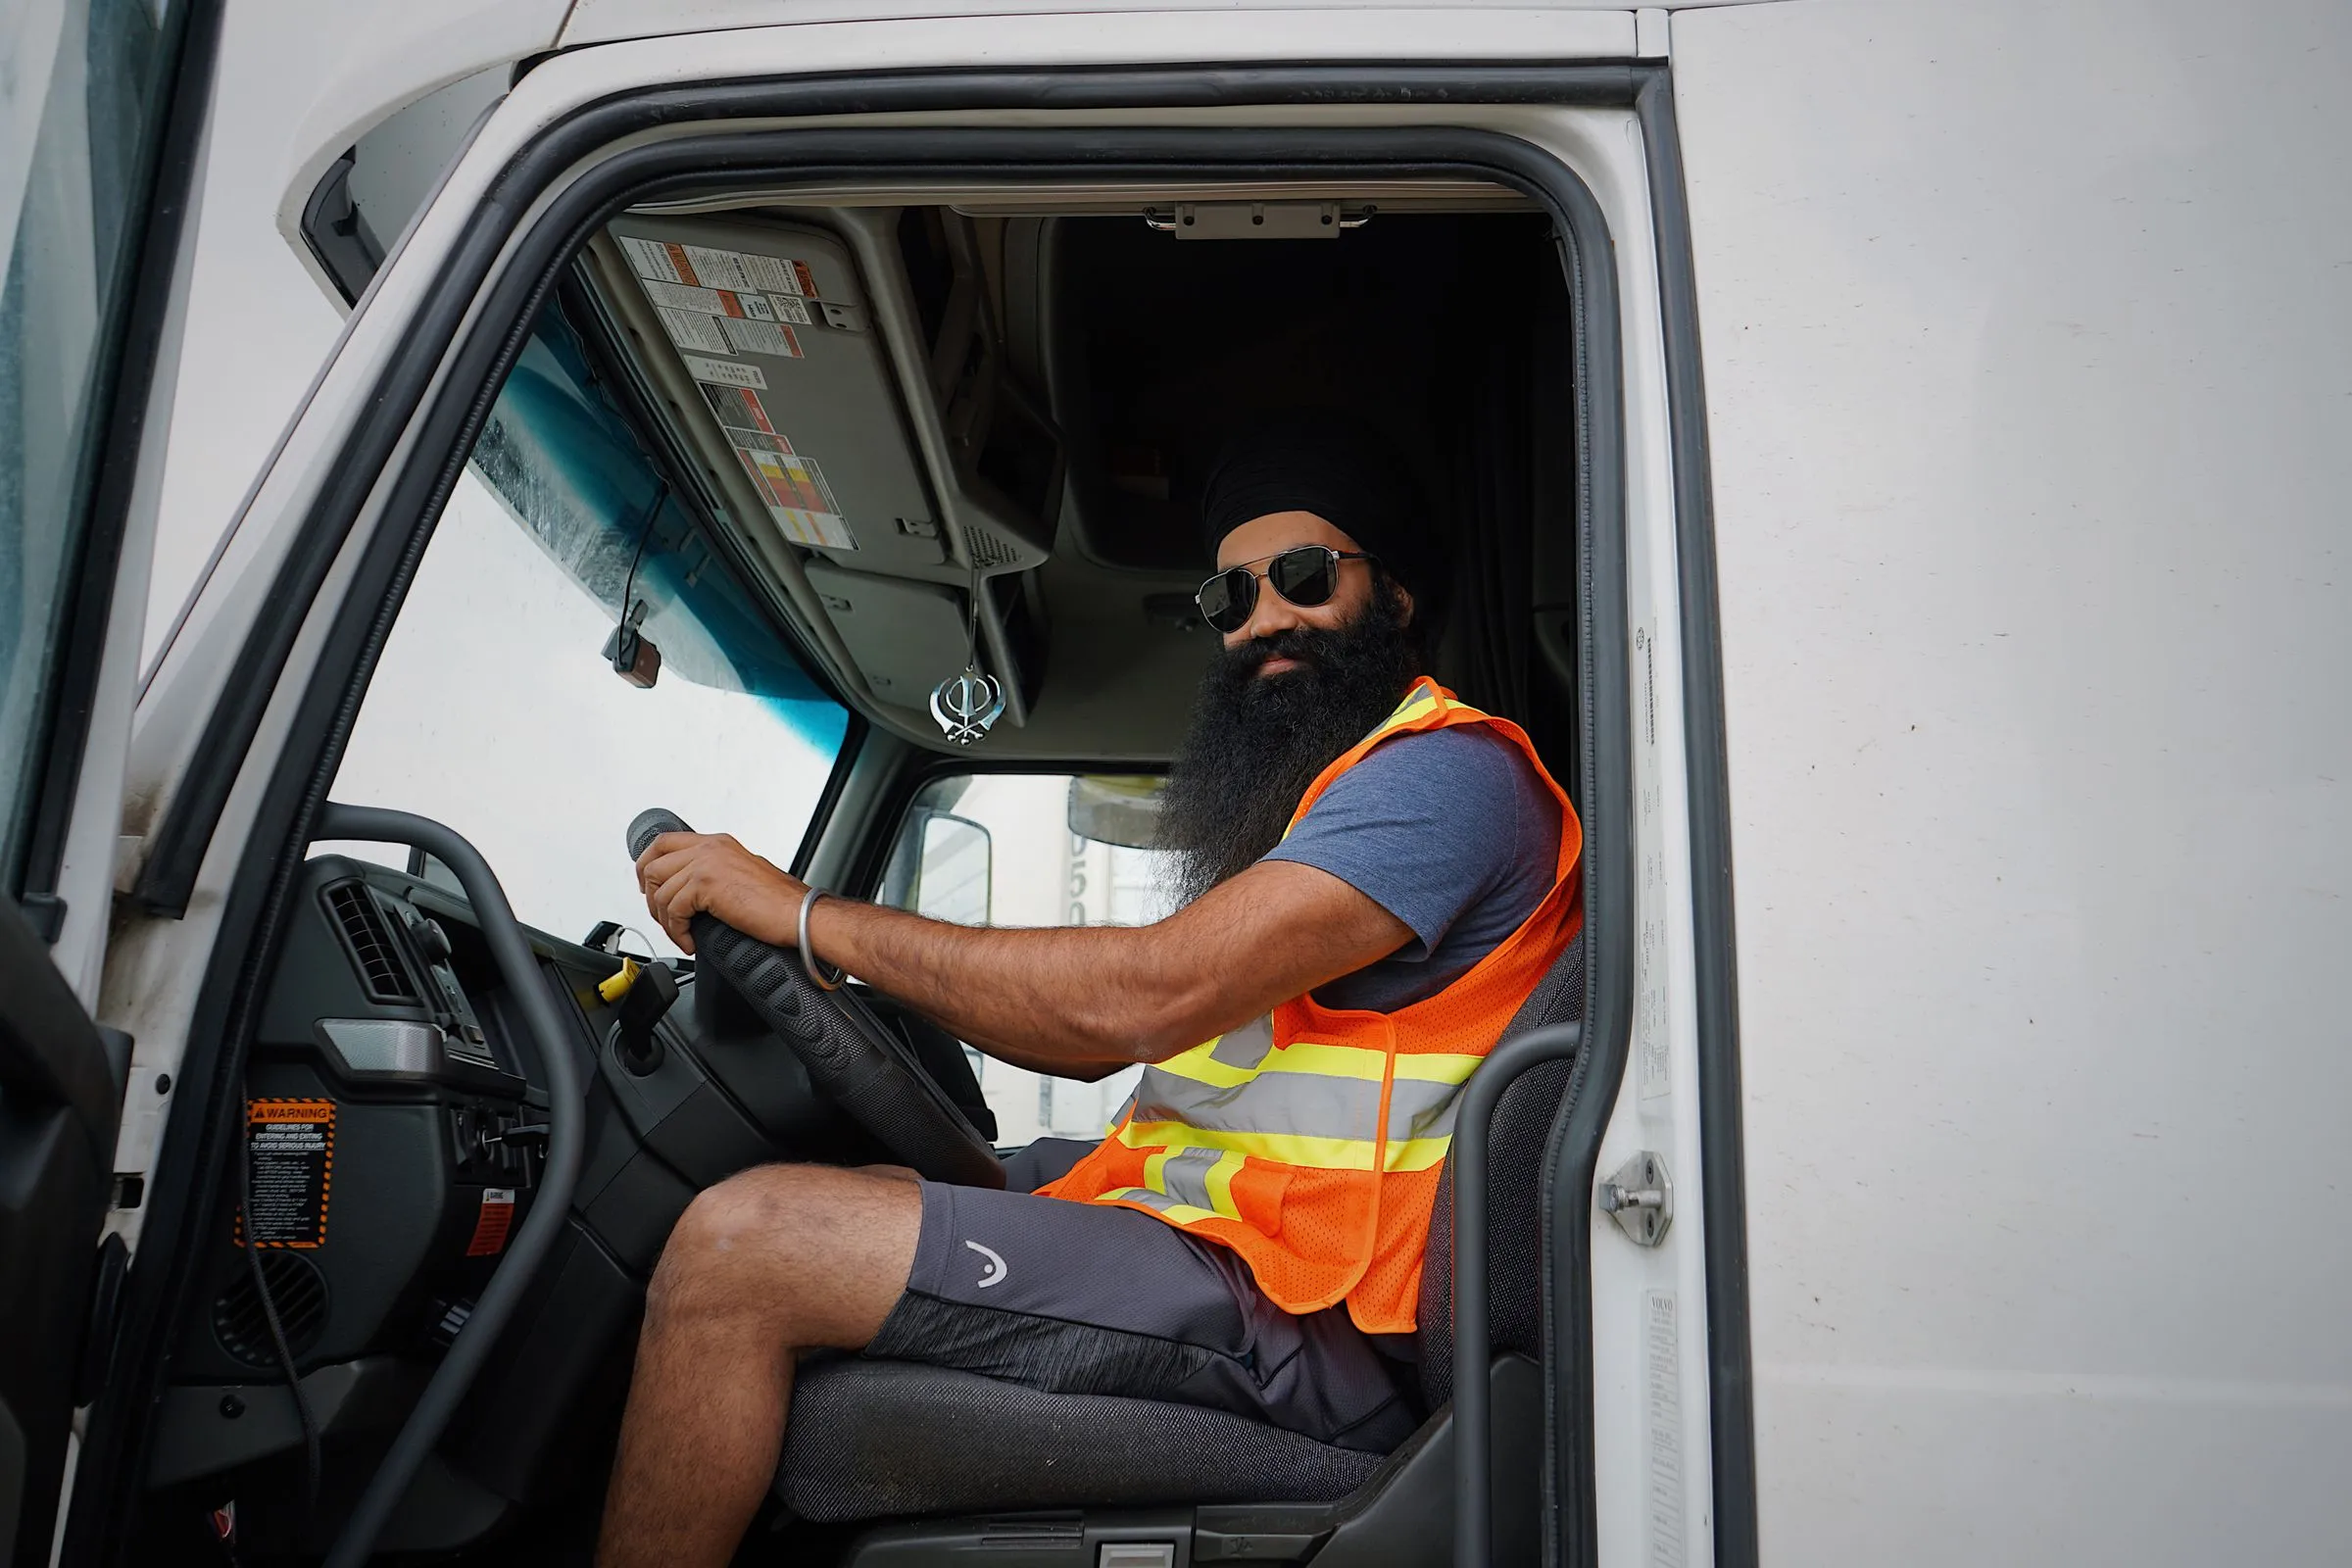
Owner-operator truck drivers
Truck depreciation and fuel shrink your T2125 income. Lenders can add capital cost allowance back, and settlement statements back up your revenue.
How it works↗Your write-offs lower your taxes. They shouldn't lower your approval.
Asim Ali helps truck drivers, trades, realtors, consultants and incorporated business owners qualify with the right program: CMHC self-employed with a 15% gross-up, insured stated income at up to 90% loan-to-value, or lenders that use bank statements.
#4 CMP Top 75 Mortgage Brokers 2026 · 4.8★ from 307 Google reviews
As featured in
Your accountant keeps your taxable income low. Banks read that number and say no. Asim shows lenders what your business really earns.
Expenses added back, a 15% gross-up or stated income, not just one line on your tax return.
Banks, credit unions, mortgage insurers, alternative and private lenders, compared for you.
Self-employed approvals depend on which lender reads your paperwork and how. These are the numbers behind the advice.
No lender has a "trucker mortgage" or a "realtor mortgage". What changes is which of these programs fits your paperwork.
Updated November 16, 2026 · Compare all programs · Try the calculator
Sole proprietors and incorporated owners with filed tax returns
As little as 5% down. Your income can be raised 15% or have expenses added back.
Read the guide ↗Two years or more in business, income on paper too low
Qualify on a reasonable income, not your tax line. 10% down, purchases only.
Read the guide ↗Same situation as Sagen, a second insurer to compare
A second insurer for stated income. 10% down and two years in business.
Read the guide ↗Most borrowers with two years of returns
Banks and credit unions average your last two years of income.
Read the guide ↗Newer businesses, bank-statement income, commission and tip earners
Uses bank statements. A business can be as new as 6 months.
Read the guide ↗Bruised credit or documents that do not fit the box
For bruised credit or unusual papers. Usually 20% down and a higher rate.
Read the guide ↗Owners whose tax arrears block a regular approval
Use home equity to pay CRA in full, then move to a regular lender.
Read the guide ↗Owner-operators buying the building their business runs from
Up to 100% of project cost for the building your business runs from.
See the program ↗


Truck depreciation and fuel shrink your T2125 income. Lenders can add capital cost allowance back, and settlement statements back up your revenue.
How it works↗
Paid on a T4A or through your own corporation? With CRA watching Driver Inc. arrangements in 2026, lenders look hard at how you are paid. A clean file wins.
How it works↗
Uber, DoorDash and courier income counts once you have a track record. We show you what works now and what to build toward.
How it works↗
Tools, vehicle and seasonal swings all hit your net income. Your trade ticket and years in the same line of work count in your favour.
How it works↗
Subcontract income on a T4A or invoices to homeowners both work. We show lenders steady work, not just one strong year.
How it works↗
Incorporated with crews and equipment loans? Lenders look at your salary, dividends and company cash flow together.
How it works↗
Dividends, salary or retained earnings: the mix you pay yourself changes what lenders see. We compare lenders that treat it differently.
How it works↗
Chair rental, tips and card sales add up. Bank-statement programs can show income your tax return does not.
How it works↗
Busy shop, modest net income? Gross-up, add-backs and stated income each fit a different file. We match yours.
How it works↗
Commission is not eligible for insured stated income, so we use your two-year average or a lender that accepts commission income.
How it works↗
Contract income, a recent switch from salary, or clients paying invoices late. Same-line-of-work history helps you qualify sooner.
How it works↗
One-person corporation billing by the day? Lenders read your contracts, salary and dividends. We present all three.
How it works↗If your tax returns show enough income after a 15% gross-up or add-backs, a full-documentation insured mortgage costs far less than stated income. On a $540,000 mortgage at 90% loan-to-value:
CMHC premium with verified income (3.10%)
Stated income premium, Sagen or Canada Guaranty (5.85%)
Premiums are added to the mortgage. Provincial sales tax on the premium applies in Ontario. See CMHC premiums.
Add back your depreciation, vehicle and home-office costs and see the difference in seconds.
Example scenarios, not real clients. Numbers use the calculator's rules, tested at 5.25% with no other debts.
Owner-operator, Surrey BCExample scenario
Problem: Two years of returns showed $46,000 and $52,000 after truck depreciation.
Route: CMHC self-employed, with depreciation added back to income.
Realtor, Brampton ONExample scenario
Problem: Insured stated income does not accept commission, and her bank wanted more history.
Route: Full documentation: two-year average of $75,000 with 5% down.
Incorporated contractor, Calgary ABExample scenario
Problem: He paid himself a $36,000 salary plus dividends from his corporation.
Route: Salary plus line 12000 dividends, averaged: $84,300.
Straight answers, checked against the insurer and lender rules on November 16, 2026.
Yes. Self-employed borrowers qualify through full-documentation lending (two years of tax returns), insured stated income programs from Sagen and Canada Guaranty, or alternative lenders that use bank statements. With verified income, CMHC self-employed allows as little as 5% down on a home under $1.5 million.
Most lenders average line 15000 of your last two Notices of Assessment, or use the lower year if your income fell. CMHC lets lenders gross up sole-proprietor income by 15% or add back eligible expenses such as vehicle costs, business use of home and capital cost allowance. For incorporated owners, lenders look at salary and dividends, and some also consider company cash flow.
It is an insured purchase mortgage where your income is tested for reasonableness instead of taken straight from your tax return. Sagen and Canada Guaranty offer it at up to 90% loan-to-value for borrowers with at least two years in business, no tax arrears and income that is not commission. The premium is 5.85% at 85.01 to 90% loan-to-value. The income you state must be true.
Often, yes. CMHC allows shorter histories when you stayed in the same line of work, bought an established business or have cash reserves. Equitable Bank accepts a registered business with 6 months in operation on bank statements. Expect a larger down payment on most alternative options.
Yes. Lenders read your T2125 or corporate statements, carrier settlement statements and bank deposits. Truck depreciation (capital cost allowance) can be added back under CMHC rules, while your truck loan payment counts in your debt ratios. A two-year history with the same carriers helps most.
Tax arrears rule out insured stated income and make bank approvals hard. The usual fix is a short private second mortgage that pays CRA in full and removes the lien, followed by a refinance with a regular lender once the debt is cleared.
Federally regulated lenders qualify you at the greater of your contract rate plus 2% or 5.25%. OSFI kept this rule in place in January 2026. Some provincially regulated credit unions set their own qualifying rules.
★★★★★“Finding a mortgage broker that knows how to present an application to a lender when you’re a seasonal worker is rare…”
★★★★★“Words cannot describe how grateful my family is for the work that Asim and Yogita have done…”
★★★★★“The Asim Ali team are an absolutely wonderful group of people! Right from the beginning, the communication was quick and professional…”
★★★★★“I had an excellent experience working with the Asim Ali Mortgage team… professional, knowledgeable, patient, and incredibly supportive.”
★★★★★“From the first conversation to the final approval, they were professional, knowledgeable and always available to answer my questions…”
★★★★★“We had an excellent experience working with Asim Ali and his team… genuinely committed to helping us find the best solution…”
Surrey office. Phone and video meetings across all three provinces.
Toronto, the GTA, Ottawa and London: land transfer tax, cash for the insurance sales tax, and Brampton trucking.
See Ontario↗
Calgary and Edmonton: ATB Financial, no land transfer tax, and the highest share of incorporated owners.
See Alberta↗
Surrey, Vancouver and the Fraser Valley: property transfer tax exemptions, credit unions and trucking.
See British Columbia↗Surrey · Vancouver · Abbotsford · Calgary · Edmonton · Toronto · Brampton · Mississauga · Oakville · London
Tell us how you are paid. Asim will tell you which programs fit, what documents to gather and what you can likely afford.